Which supplier documents support your costs and deductible VAT in Colombia
In short
- Costs, deductions and deductible VAT (IVA descontable) can be backed by an electronic invoice, an electronic POS ticket, or the support document your company issues when it buys from someone who does not invoice.
- A paper POS ticket no longer works for that (Tax Code, art. 616-1, paragraph 2).
- An invoice on credit only supports costs and deductible VAT once your company confirms receipt before the DIAN (events 030 and 032).
- The most common leak is petty cash: the expense gets paid, but the invoice never reaches the books.
Every month, companies lose deductions on documents that did exist but were not the right document, or that never reached the accountant. It is not about how much you spent, but about what you back it with.
The three documents that do work
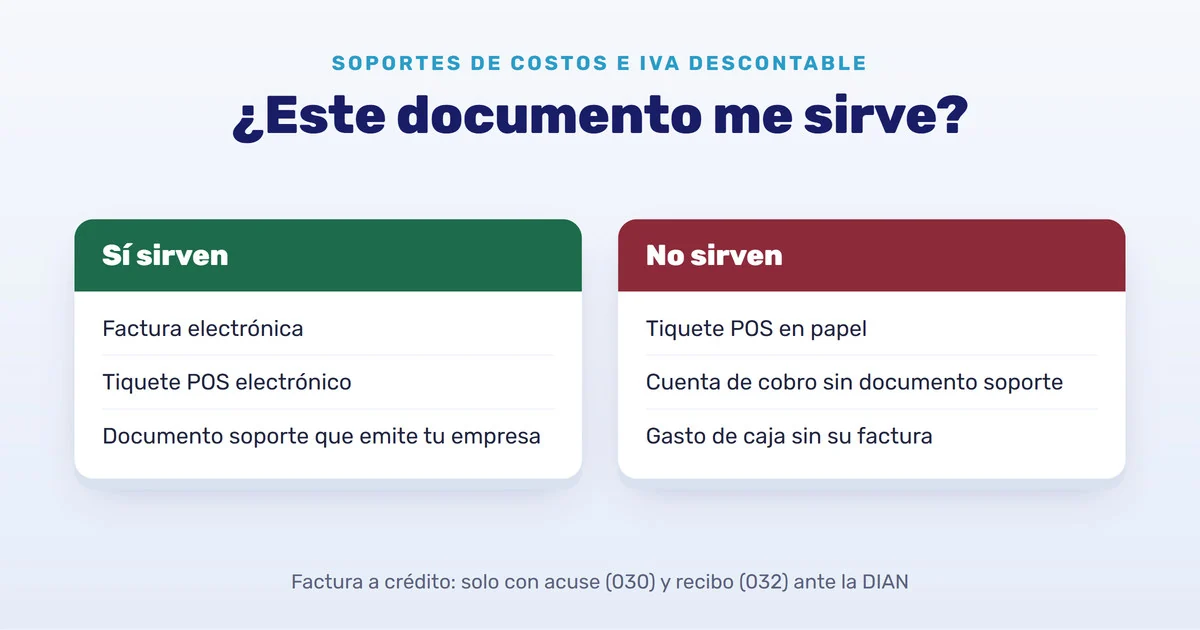
- Electronic sales invoice. The one a supplier that invoices electronically issues to you. It reaches your email as a ZIP with the XML and the PDF, and it is registered with the DIAN under its CUFE.
- Electronic POS ticket. The electronic equivalent document you get at a point of sale. It carries its CUDE and a QR code, and it is also registered with the DIAN (DIAN Resolution 000165 of 2023, art. 16).
- Support document. When you buy from someone who is not required to invoice, for example an individual who provides you a service, your company issues the document and validates it with the DIAN. The bill of charges they hand you is not enough on its own.
What no longer works
- A paper POS ticket, the classic cash register receipt. It does not entitle you to costs, deductions or deductible VAT (Tax Code, art. 616-1, paragraph 2). If your supplier still hands you one, ask for the electronic invoice.
- A bill of charges without its support document. It tells you how much to pay, not how to back the cost.
- An invoice issued to “final consumer”. It does not identify your company as the buyer. Ask for it to be issued to your NIT.
Invoices on credit need one more step
If the supplier sells to you on credit, the invoice only supports costs, deductions and deductible VAT once your company confirms to the DIAN that it received it: the acknowledgment of receipt (event 030) and the receipt of the goods or service (event 032), per DIAN Resolution 000085 of 2022, art. 34. These are RADIAN events and the buyer records them, not the supplier.
Which events to send and when is your accountant’s call. What cannot happen is that nobody notices they are missing.
The petty cash leak
Fuel, the lunch for the meeting, the spare part bought in a hurry. They are paid from petty cash, recorded as an expense, and the invoice stays in the glove box or in someone’s inbox. Without the invoice recorded, that expense is not deductible.
The fix is not asking everyone for more discipline. It is making “record the expense with its invoice” one step instead of two.
Foreign suppliers
If a foreign supplier’s invoice carries a tax number from its country (VAT or Tax ID), it is recorded with that number. The third-party NIT 444444 is only for foreign companies whose country does not use a tax number, and misusing it can be penalized (DIAN Resolution 000227 of 2025, art. 1.3.5.2.1, paragraph 6).
How the IAnalitics SaaS Platform handles it
- In Purchases and expenses each document has its type: electronic invoice, electronic POS ticket, bill of charges, support document or receipt.
- Electronic invoices come in without typing: you upload the ZIP or XML from the email, or pull it from the DIAN by its CUFE, and record events 030 and 032 from there. To bring in many at once, Import from the DIAN loads the list you download from the DIAN portal and records them in a batch, skipping the ones already there.
- The platform flags invoices on credit that have no acknowledgment or receipt.
- For petty cash expenses, the Save with invoice button records the expense with its invoice in one step, and the books take it from the purchase, never twice. The “Without invoice” filter shows the expenses that still lack one.
- The support document is signed and validated with the DIAN when you save it.
The details are in the Accounting manual and the E-invoicing manual (both in Spanish). None of this replaces your accountant’s judgment: it saves them the part of chasing documents. If you want to see it with your own purchases, book a demo.
Found this useful? Every week we share guides like this one on LinkedIn. Follow IANALITICS on LinkedIn →